
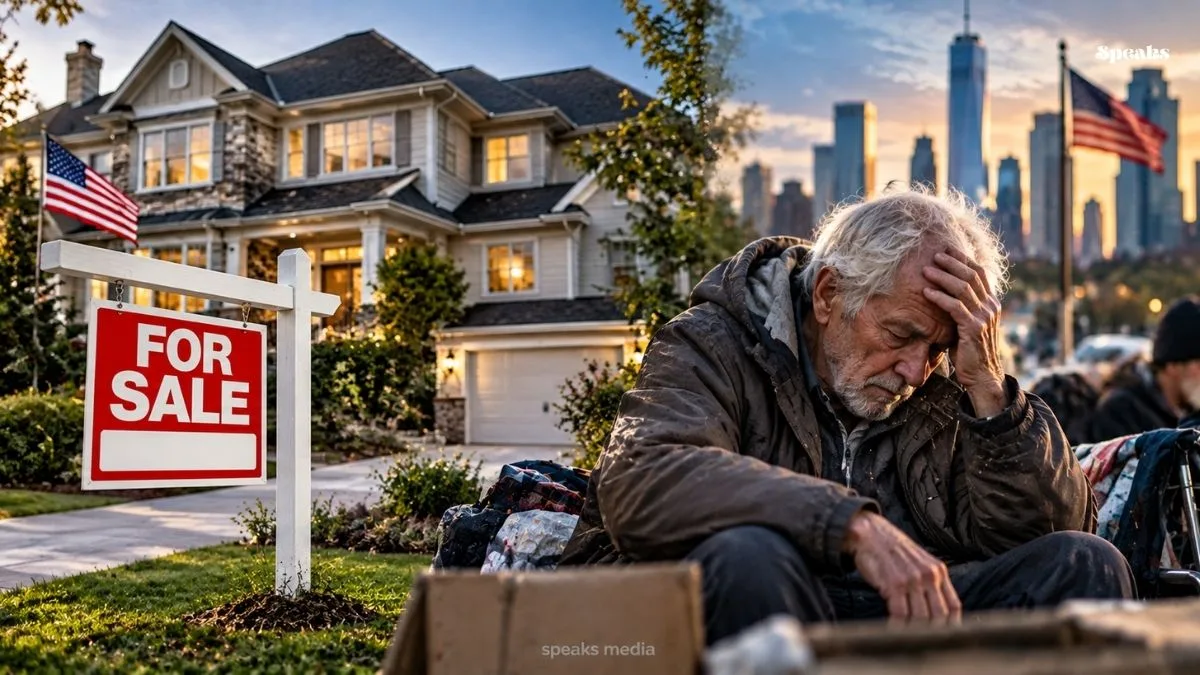
A different picture has emerged regarding the economic condition of the elderly in America, which is quite startling. It is called ‘house-rich, cash-poor’. Under this, nearly 10 million elderly (senior citizens) in America are forced to live in poverty, even if they own an expensive house.
Senior citizens in America have plenty of housing assets. On the other hand, poverty is increasing among them. Millions of seniors in the country 65 and older own large assets in the form of homes, yet nearly 10 million Americans live in poverty. Their poverty rate reached 15.4%, the highest of any age group.
10 million Americans live in poverty
Nearly 10 million Americans age 65 and older are projected to live in poverty in 2025 under the supplemental poverty measure, according to a new AARP Foundation analysis of US Census Bureau data. Their poverty rate reached 15.4%, the highest of any age group. These results contradict common beliefs about aging in America. Older generations are believed to have accumulated enormous wealth, much of it in their homes, and are expected to pass trillions of dollars to their heirs in the coming decades.
What Joel Berner said
Joel Berner, senior economist at Realtor.com, says these figures reflect different groups of people. ‘There are two things at work here,’ he says. First, these net worth figures are mostly skewed towards high net worth seniors. Seniors who do not own a home are more likely to face poverty, so both may be true for different segments of the senior population. Home ownership does not necessarily solve this paradox.
Second, even in the case of senior home owners, their housing assets (home-related assets) are such that they cannot be easily converted into cash (illiquid). Unless the home is sold or a loan is taken out against it, it cannot be used to pay groceries or utility bills, so many seniors are house rich but cash poor.
increase in statistics
Different scales used to measure poverty among the elderly in the US also show this difference. According to the government’s official poverty measure, 9.8 percent of people aged 65 and over were in poverty in 2025. This number was around 64 lakhs. Under the supplementary poverty measure, this figure rises to 15.4 percent, or about 1 crore people.
The Supplemental Poverty Measure (SPM) also includes expenses such as medical expenses, which have a greater impact on the elderly. Even though health facilities like Medicare are available, the elderly may have to spend a lot of money out of their own pocket. For people suffering from serious health problems, these expenses can quickly deplete their remaining income.
At the same time, poverty statistics alone do not fully reflect the severity of economic pressures. According to the University of Massachusetts Boston’s ‘Elder Index’, in 2025 more than half (53%) of elderly people live alone and more than a quarter (25%) of elderly couples do not have enough income to meet their basic needs. Compared to 2022, this figure has increased by 5 percentage points in the case of elderly people living alone and by 4 percentage points in the case of elderly couples. The purpose of this index is not only to see whether a person is in poverty or not, but also to find out whether his income is sufficient to lead a dignified and basic life.
The income needed to cover basic expenses for an elderly homeowner with a mortgage increases from $36,300 in 2022 to $39,396 in 2025. About two-thirds of this increase was due to an increase in household spending. Even home owners without mortgages were not untouched by this. During that period, their household expenses increased by about 14% as costs related to home ownership increased.
Property taxes will increase by 31% between 2019 and 2025
According to the ‘2026 State of the Nation’s Housing’ report by Harvard University’s Joint Center for Housing Studies, property taxes for all homeowners are expected to rise 31% between 2019 and 2025, while the average monthly insurance premium for homeowners is expected to rise 72%. Homeowners whose homes were completely debt-free (free and clear) saw average housing costs increase by 35% between 2019 and 2024, while homeowners’ incomes increased by 23%.
Richard Johnson, vice president of financial security at the AARP Public Policy Institute, says rising costs are affecting the incomes of all types of households, and older Americans are feeling the pinch in particular. And when income isn’t enough to cover these expenses, home equity (your share of the home’s value) can provide another source of security. Research shows that many people do this after all.
According to Boston College’s Center for Retirement Research, more than 40% of households that started with at least $100,000 in investable assets used their home equity in retirement—either by taking out a home loan or moving into a lower-cost home.
A separate study by the center found that the cost of long-term care may also be a factor. A 2025 study found that sudden increases in long-term care costs forced retirees to tap into their home equity and reduced the wealth they expected to leave to their heirs.
These costs can be very heavy on normal retirement income. According to Harvard research, only 24% of households where someone was age 75 or older had enough money left over to afford daily visits to a paid home health aide after daily expenses. But the easiest way to use housing wealth is to sell your big house and move to a smaller and cheaper house, which is not necessary.
According to Berner, ‘The lack of housing prevents the younger generation from becoming home owners, but this affects the older generation as well. For landlords, there are concerns about abandonment and liquidity, and for seniors living in rentals, rising rents on fixed incomes are a problem. In theory, many older homeowners could move up to a smaller home and convert some of their home equity into cash, but there aren’t many opportunities to do so in the market (just like there aren’t many opportunities for first-time home buyers) because tiny homes (starter homes) are in such short supply. Instead, they are stuck with larger homes that are expensive to maintain, creating more cash flow problems.
Older people who live in rentals do not have equity that they can convert into cash. According to Harvard, in 2023, 58% of renter households headed by people age 65 or older were burdened with housing costs. This number is approximately 45 lakh families.
In America, large amounts of wealth are expected to be transferred to the next generation in the coming decades. Cerulli Associates estimates that $124 trillion will be transferred by 2048, of which $105 trillion will go to heirs, but more than half of the total is expected to come from ultra-high net worth households, who make up just 2% of all households. For everyone else, aging and rising household costs may mean some of that wealth may have to be spent sooner.


